
Captive vs. Independent: Which Path Pays More in South Carolina?

Built for the Pearson VUE Exam
South Carolina specific prep, mobile and self-paced.
Quick Answer
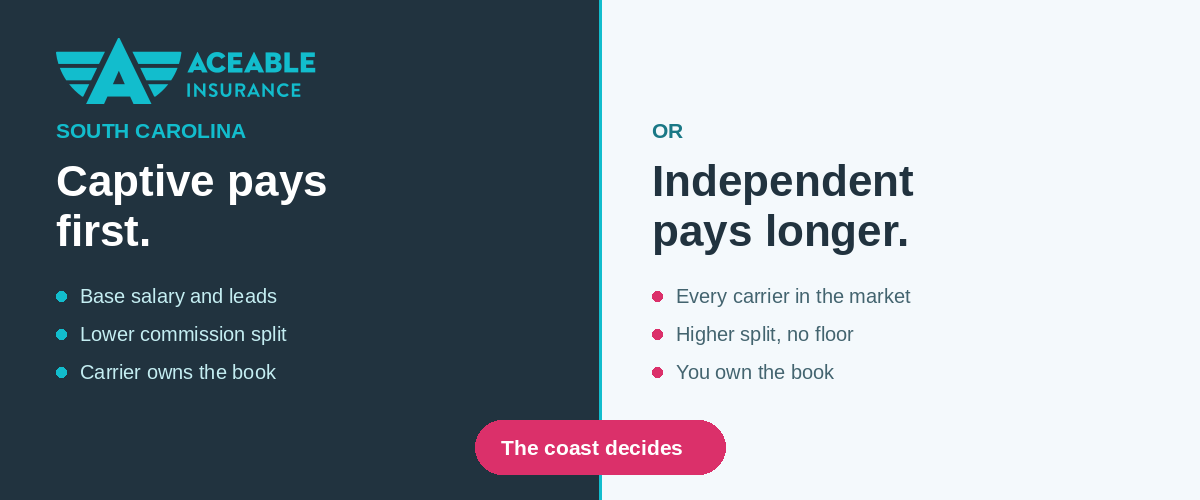
- Captive trades: ceiling for the floor. You get a base, leads, and structured training in your first year, and you accept a lower commission split and a single carrier's appetite in return.
- Independent trades stability for access. Higher splits and every carrier in the market, but commission-only income while you build, and no one handing you a pipeline.
- The coast is the South Carolina-specific variable. When national carriers pull back from high-wind zones, a captive agent cannot follow the client, and an independent agent can.
Most comparisons of these two models are written for no state in particular. South Carolina is not no state in particular. A coastline that some carriers will not write, fast inland growth around Greenville and Columbia, and no pre-licensing education requirement combine to make both models workable here for different reasons. The question is not which one is better. It is which one fits the next three years of your life.
How Does Each Model Actually Work?
What Captive Looks Like
- Carriers represented: one.
- Income structure: typically a base salary plus commission, which smooths the ramp while you learn.
- Commission split: lower than independent, because the carrier is funding your training, your leads, your office, and your brand recognition.
- Lead flow: provided. This is the single most underrated part of the deal for a new agent.
- Appointments: handled for you as part of onboarding.
- Book ownership: the carrier generally owns the client relationships.
What Independent Looks Like
- Carriers represented: as many as you can get appointed with, often starting through an IMO or FMO.
- Income structure: commission only. No base, no floor.
- Commission split: higher, because you are covering your own overhead and generating your own business.
- Lead flow: yours to build. Referrals, networking, marketing spend.
- Appointments: you pursue them, and new agents without a track record often struggle to win direct appointments early.
- Book ownership: you own it, which is the part that compounds.
Neither column is the good one. They are two different bets on when you want the money. Our overview of carrier appointmentsPre License Do South Carolina Insurance Agents Need A Carrier Appointment To Sell Insurance Resources explains the mechanics that sit underneath both models.
Which Path Pays More in Your First Year?
Captive, almost always, and it is not close.
A base salary in a year when you are still learning to quote is worth more than a higher split on business you have not written yet. New independent agents commonly underestimate how long the pipeline takes to fill and how much of year one is spent on activities that generate no commission at all.
The honest framing is this. Captive pays you to learn. Independent asks you to pay for the privilege, in the form of savings burned while you build. Both are reasonable. Only one of them is survivable without a cash cushion, and our breakdown of first year earningsPre License What Insurance Agents Actually Earn In Their First Year Resources gets specific about what the ramp really looks like.
Over a full career, the ranking usually flips, for reasons that have less to do with commission rates than with what you own at the end. More on that below.
Why Does South Carolina's Coast Change the Math?
This is the part a national comparison cannot give you.
Along the coastal corridor from Myrtle Beach through Charleston to Hilton Head, wind and hail coverage is frequently excluded from the standard homeowners policy. The client has to source it separately, either from a private market carrier willing to write the risk or from the South Carolina Wind and Hail Underwriting Association, the state's residual market for essential coastal property coverage. Flood is a third policy again through the federal program.
Now apply the two models to that reality. A captive agent whose carrier restricts new business in high wind zones has nothing to offer the client standing in front of them. An independent agent with surplus lines access, an association appointment, and specialty coastal markets can place the risk and keep the relationship. Same license, same state, completely different conversation.
Inland, the picture reverses. The I-85 corridor, Greenville, and Columbia are growing fast with new housing, relocations, and small business formation. That is ordinary, placeable personal and commercial lines business, and it is exactly the environment where a captive carrier's brand and lead flow are worth the lower split.
So geography is a real input here. If you plan to build a coastal book, independence is worth more to you sooner. If you are building in the Upstate or the Midlands, captive stays competitive far longer.
What Is Your Book of Business Actually Worth?
Here is the factor that outweighs every commission percentage discussed so far.
An independent agent's book is a sellable asset. Agency books are commonly valued as a multiple of annual commission revenue, and that multiple is why independent agents can exit a career with something to sell, borrow against, or hand to a successor. The renewals keep paying whether or not you write anything new, and the asset has a market.
A captive agent's book generally is not theirs. Leave the carrier and the clients stay. You take the skills, the reputation, and the relationships you can rebuild, but not the equity.
That is not an argument against captive. It is an argument for knowing the terms. Captive pays you in stability and training. Independent pays you in ownership. If nobody has said that out loud to you before signing a contract, it was not because it is complicated.
Choose a State and Course
Captive or Independent, By Numbers
Put figures behind the decision before you sign anything.
What Can Slow Down Your Earning Potential in Either Model?
- Starting independent without enough savings to cover three to six months of living expenses and business startup costs
- Staying captive too long after you have outgrown the training and lead support, which caps your commission rates and limits your product offerings
- Not pursuing both P&C and Life and Health licenses, which limits cross-selling regardless of agency model
- Ignoring South Carolina's coastal niche if you are independent. Wind, flood, and Beach Plan coverage is where the underserved demand and higher margins live.
- Not planning for South Carolina's CE requirements (24 hours every two years, including 3 hours of ethics), which can interrupt your selling activity if left to the last minute)
Choose Your Path and Start Building
Since South Carolina does not require pre-licensing education, you can go from studying to licensed in as little as two to three weeks. The most common SC licensing questions are answered in our guide. That speed advantage means you can start earning, start learning the market, and start making the captive-vs-independent decision with real-world data rather than hypothetical projections.
Aceable Insurance offers exam prep designed for South Carolina candidates targeting the Pearson VUE exam. With mobile-friendly content, practice tests, and a learning experience built for career changers and newcomers, Aceable gets you licensed fast so you can start building, whether that is within a captive agency or on your own.
Charleston to Myrtle Beach
Your future in the insurance industry starts now.