
Is Insurance Really a Recession-Proof Career?

Economy shrugs. Policies still renew.
People still need coverage, and they still need an agent.
Quick Answer
- Insurance remains stable during recessions because coverage is legally required or contractually mandated for homes, vehicles, and businesses
- The industry demonstrated resilience during the 2008 financial crisis while other sectors experienced massive job losses
- Licensed insurance professionals can start earning within weeks through state-approved pre-licensing education and examinations
Insurance agents generally keep working through recessions because much of what they sell is required by law, by lenders, or by federal enrollment calendars. New sales of optional coverage slow and clients shop harder on price, so income can dip even when jobs hold. Agents with a renewing book and a mix of required and optional lines tend to feel a downturn as a slow quarter rather than a crisis.
Is insurance really recession-proof?
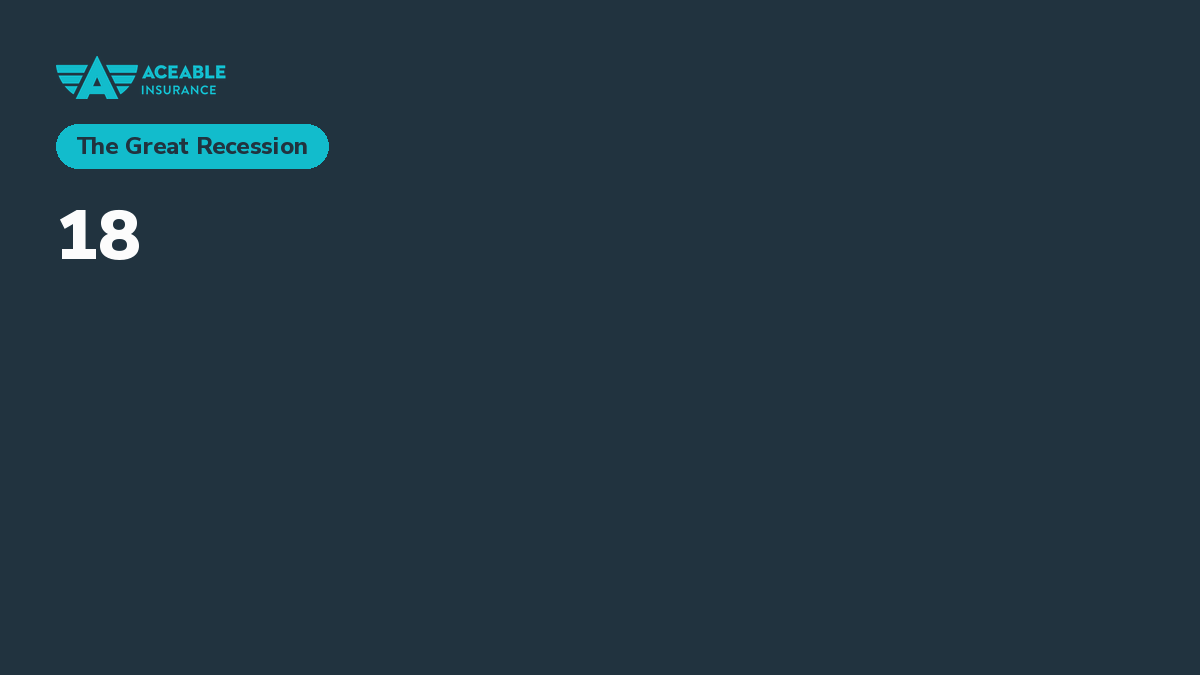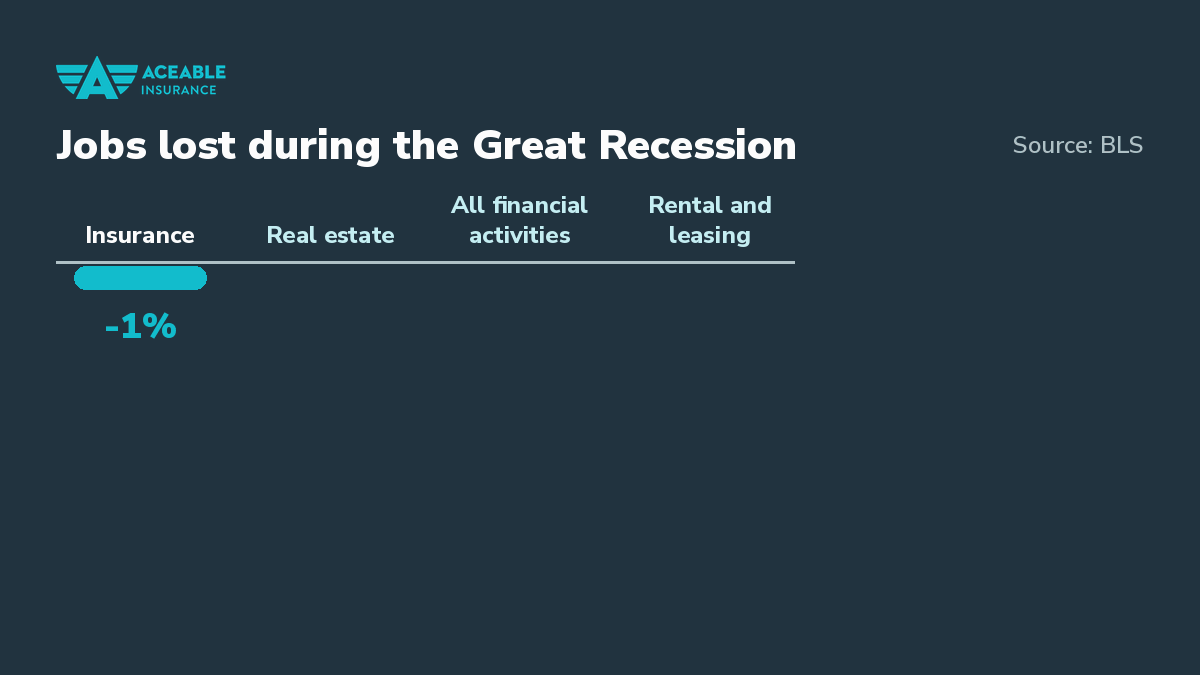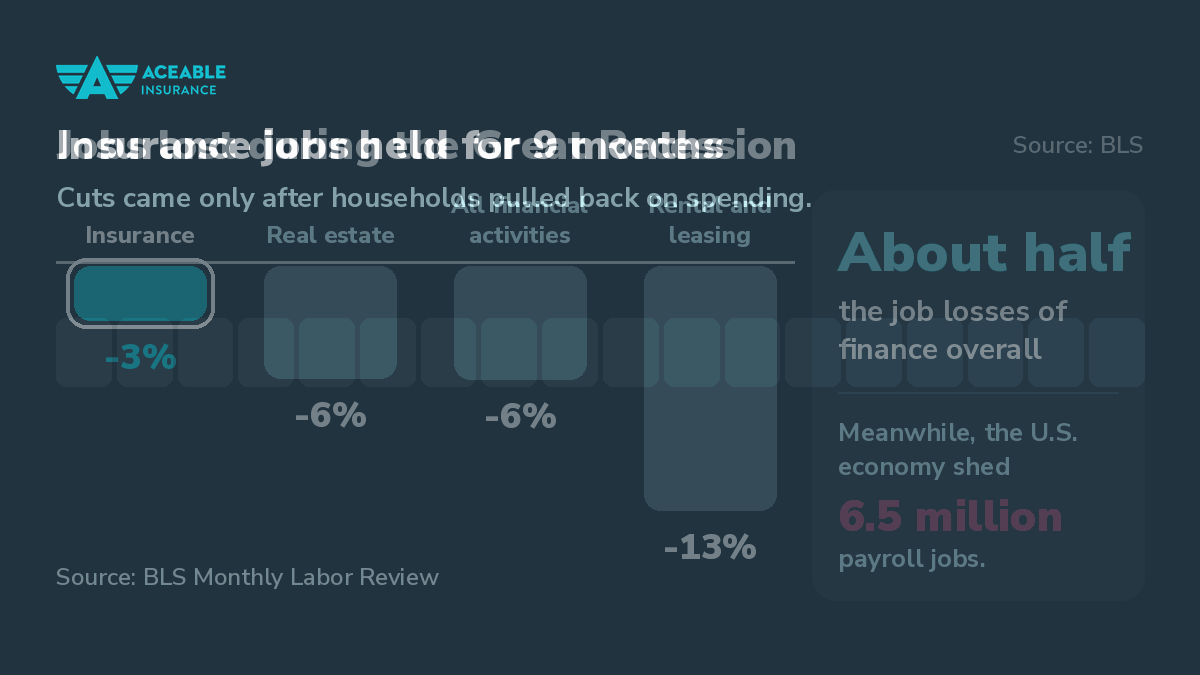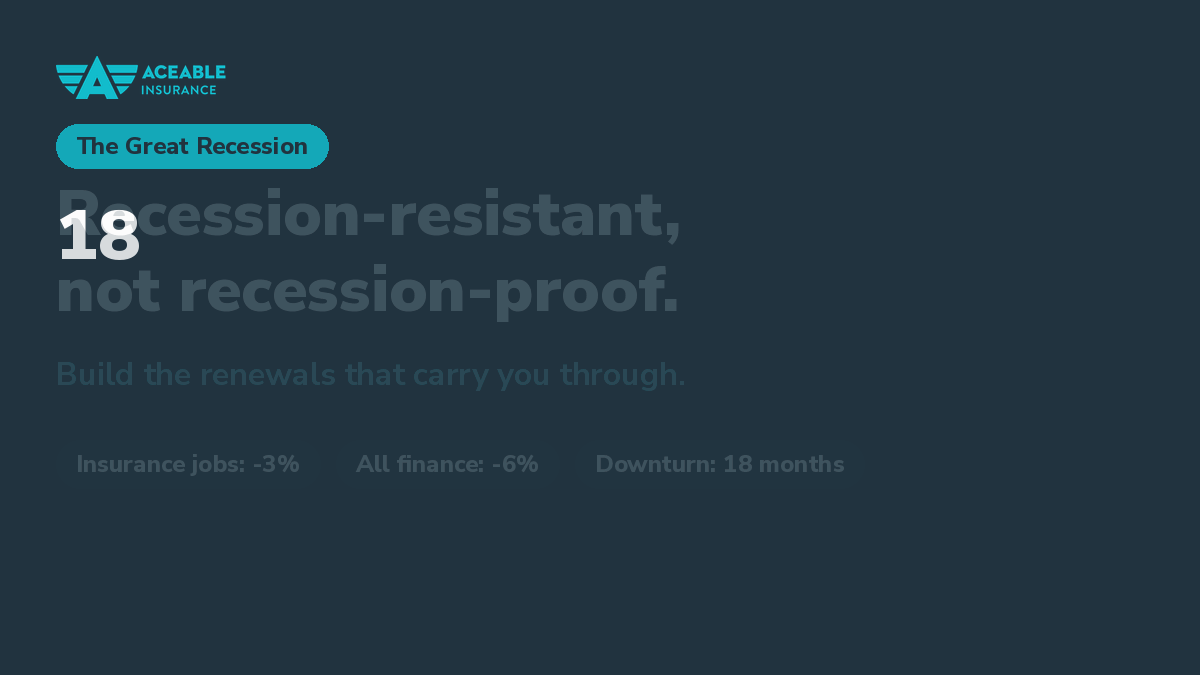
No industry is. But the data shows insurance bends far less than most. A BLS analysisMlr 2011 04 Art7full.pdf Opub of employment from the start of the Great Recession to its official end found these changes:
- Insurance carriers and related activities: Down about 3 percent.
- All financial activities: Down nearly 6 percent.
- Real estate: Down nearly 6 percent.
- Rental and leasing services: Down about 13 percent.
Over that same stretch, the U.S. economy shed 6.5 million payroll jobs, according to the BLS commissionerArchives Jec_07022009.pdf News.release.
Why insurance held up longer than banking
BLS found insurance employment was essentially unaffected for the first nine months of that recession. Job cuts came only after households pulled back on insurance spending, which fell at an annualized rate of 4.7 percent in the crisis's worst quarter.
In other words, insurance was a late and shallow casualty, not an early one.
Which insurance lines hold up best in a downturn?
The answer depends on who requires the coverage. Here is how the main lines stack up.
Coverage the law requires
- Auto liability: Virginia ended its pay-a-fee alternative to insurance, per the Virginia DMVNews New Laws Take Effect Today July 1 2024 Dmv.virginia.gov, leaving New Hampshire as the notable exception to state auto insurance mandates.
- Workers' compensation: Texas is the only state that lets any private employer opt out of the system, according to a state insurance studyWcreg Documents Nonsub.pdf Reports from Texas regulators. Everywhere else, most employers must carry it.
Coverage lenders require
- Homeowners: Mortgage lenders make property coverage a condition of the loan, so it stays in force as long as the mortgage does.
- Flood: Federal rules require flood insurance on high-risk properties with federally regulated mortgages, as the GAO explainsGAO 21 578 Products.
Coverage on a federal calendar
- Medicare plans: Open EnrollmentOpen Enrollment Health Drug Plans runs October 15 through December 7 every year, recession or not, and plans change annually.
Coverage people can postpone
- New life insurance: The 14 percent drop in new individual life premiums shows how fast optional purchases stall.
- Extras and higher limits: Clients under pressure ask about higher deductibles or trimming optional coverages.
Choose a State and Course
Top first-year earners clear six figures. Spoiler: they all started the same way.
See our FREE salary guide to what you could earn in your state.
How does a recession change an agent's paycheck?
New business slows first. Fewer home sales and car purchases mean fewer brand-new policies to write.
Premium changes flow through to you. BLS notes that commission depends on the type and amount of insurance sold, so when clients trim coverage, commission shrinks with it.
Retention becomes the job. Clients shop harder at renewal, and the agent who calls first usually keeps the account.
Why renewals work as a shock absorber
Renewal commissions keep paying on policies you wrote in good years. An agent with a mature book loses some growth in a downturn, while an agent with no book loses the whole paycheck.
That is why the first-year income ramp matters so much to timing.
How do you build a recession-resistant book of business?
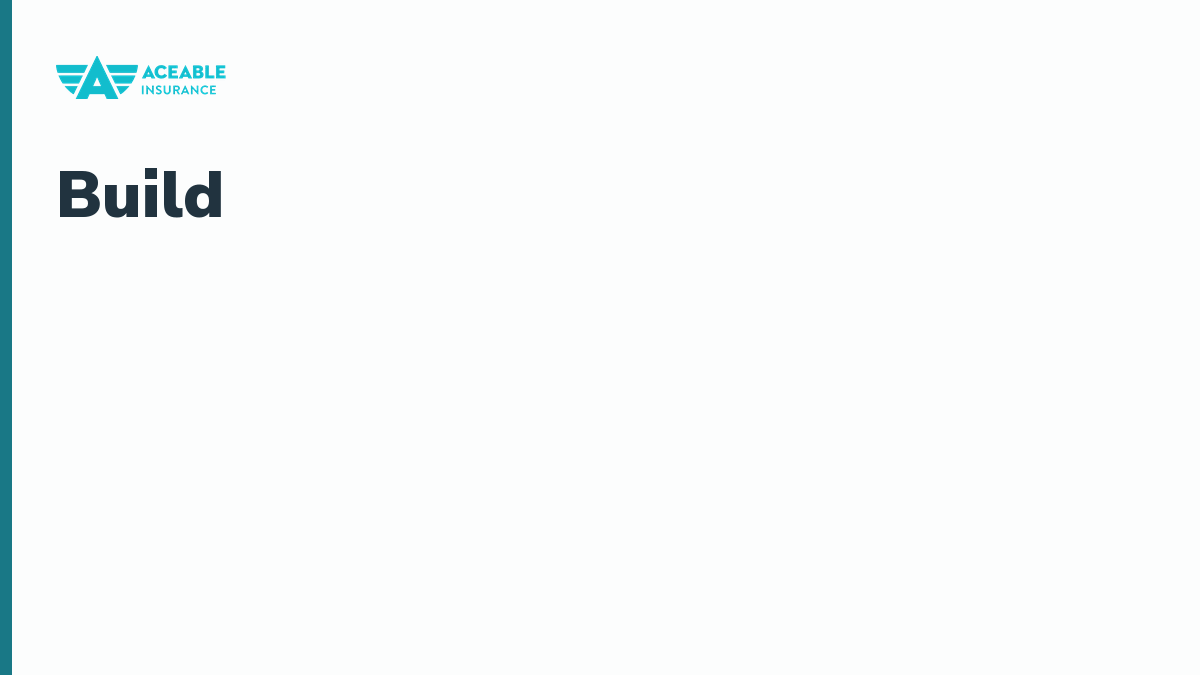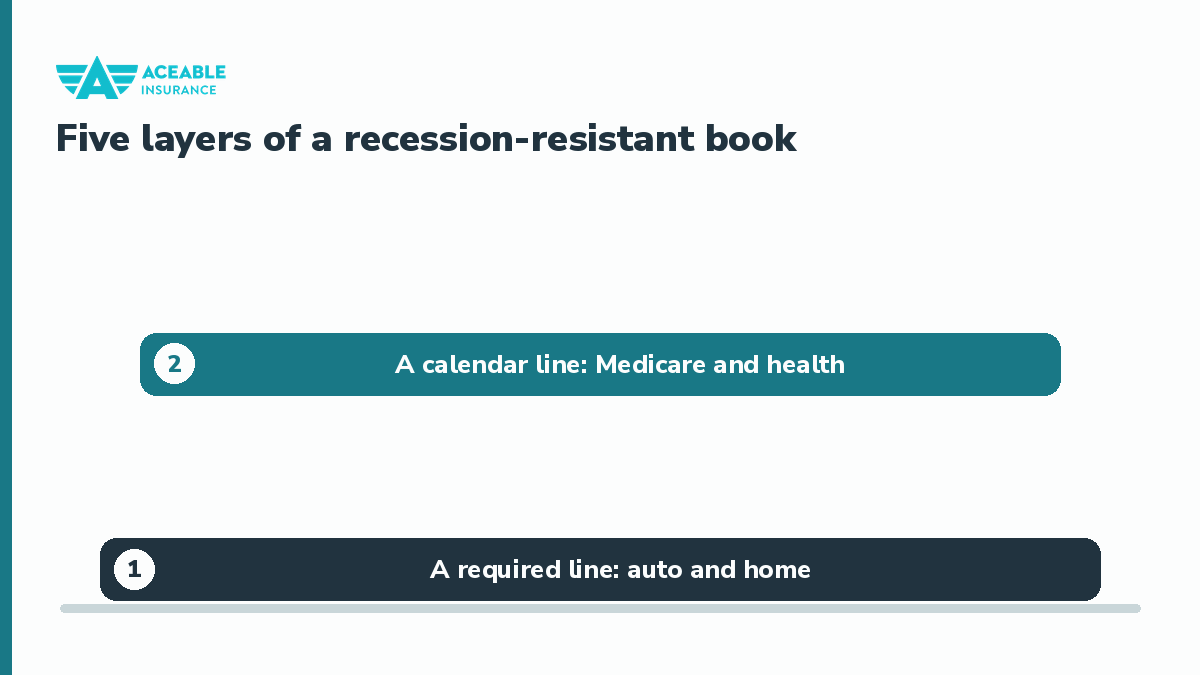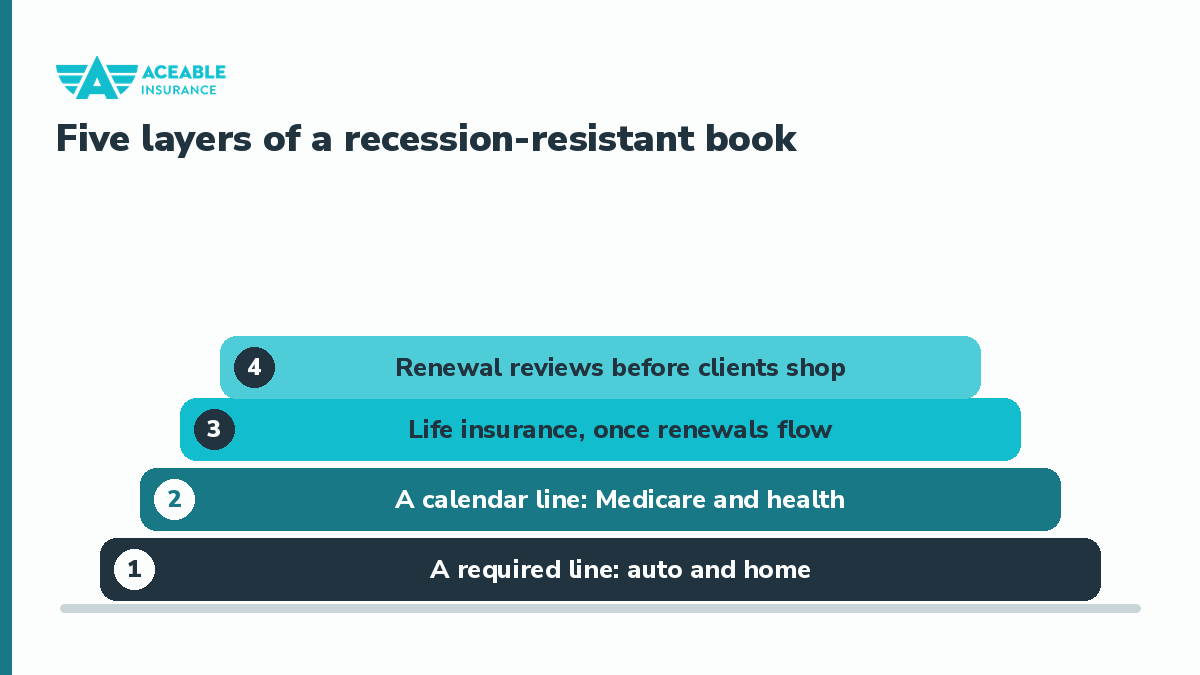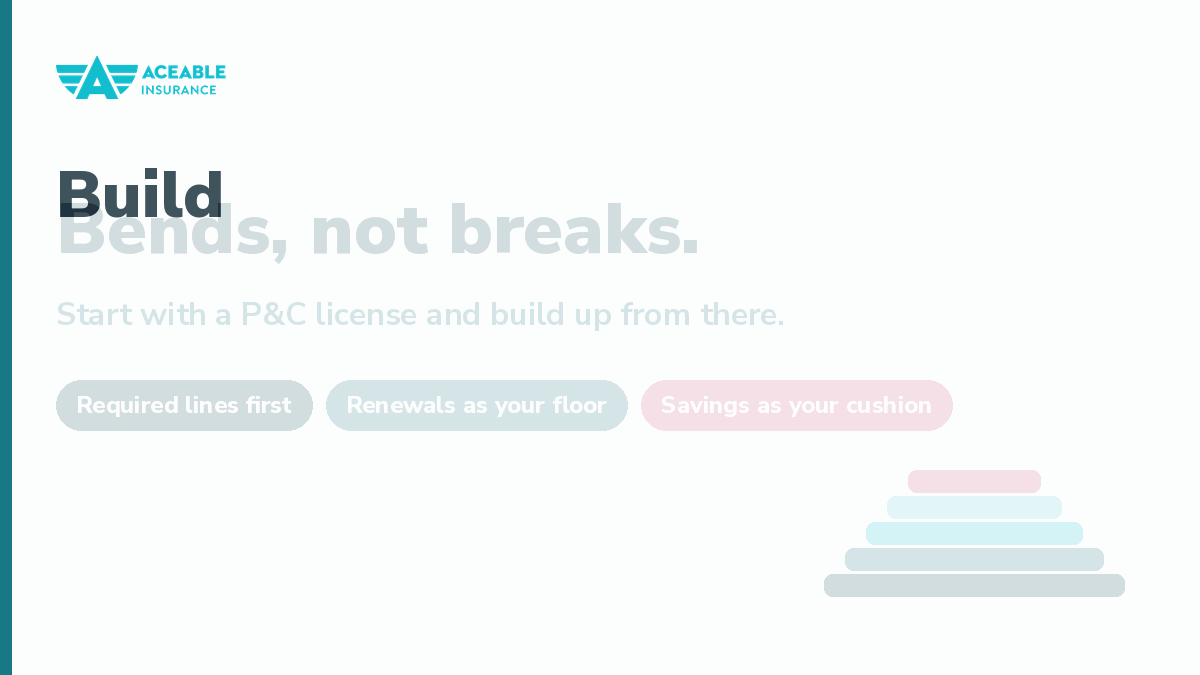
- Anchor on a required line. A P&C license puts auto and homeowners, the most mandated coverage, at the base of your book.
- Add a calendar line. Medicare and health enrollment windows arrive on schedule regardless of the economy. Weigh the life and health license.
- Layer in life once your base renews. Life sales slow in downturns, but they pay well in steady years.
- Review renewals before clients shop them. A proactive call beats a cancellation notice.
- Hold a cash reserve sized to your slowest quarter. It keeps a dip from forcing a career decision.
- Stress-test your income every quarter. Use the calculator above to see how many months your renewals and savings would carry you through a slowdown.
What can slow down an agent's income in a downturn?
- Relying on one optional product. Life-only or add-on-heavy books feel cutbacks first.
- A book too young to renew. Year-one agents have no renewal cushion yet.
- Depending on paid leads. Lead spending is hard to justify when conversion rates slip.
- Chargebacks from cancellations. Early cancellations can claw back commissions already paid.
- Single-carrier dependence. When one carrier tightens what it will write, your whole pipeline narrows.
How long does it take to get licensed before the next slowdown?
Most people finish licensing in four to eight weeks, and faster where no course is required. State rules vary widely, from no required hours in some states to hundreds in others, so check your state before you set a start date.
Our step-by-step guide shows how to get licensed, and our overview of insurance lines helps you pick where to start.
Recession questions agents ask
Do insurance agents get laid off in recessions?
Some do, but far fewer than in most industries. Insurance industry employment fell about 3 percent during the Great Recession, compared with nearly 6 percent across financial activities.
Which insurance license is most recession-resistant?
Property and casualty, because auto liability and lender-required homeowners coverage stay in force when budgets tighten. Adding life and health spreads the risk further.
Should you start an insurance career during a recession?
It can be a reasonable time to start, since required coverage keeps renewing. Build a savings cushion first, because new sales of optional products can slow.
How does Aceable Insurance help you get licensed before the next downturn?
The best time to build a renewing book is before you need it. Aceable Insurance offers state-approved pre-licensing designed for busy adults: short mobile lessons, clear explanations, and practice that shows you where you stand before exam day.
Still deciding whether this is a good career for you? Read that first.
Give your paycheck a raincoat.
Your future in the insurance industry starts now.