
Why Is Phoenix One of the Best Cities for Medicare and Retirement Insurance Careers?
Phoenix has the retirees. You bring the license.
Medicare plans fall under the health line of an Arizona license. Our exam prep is built to the state exam outline and goes wherever your phone does.
Quick Answer
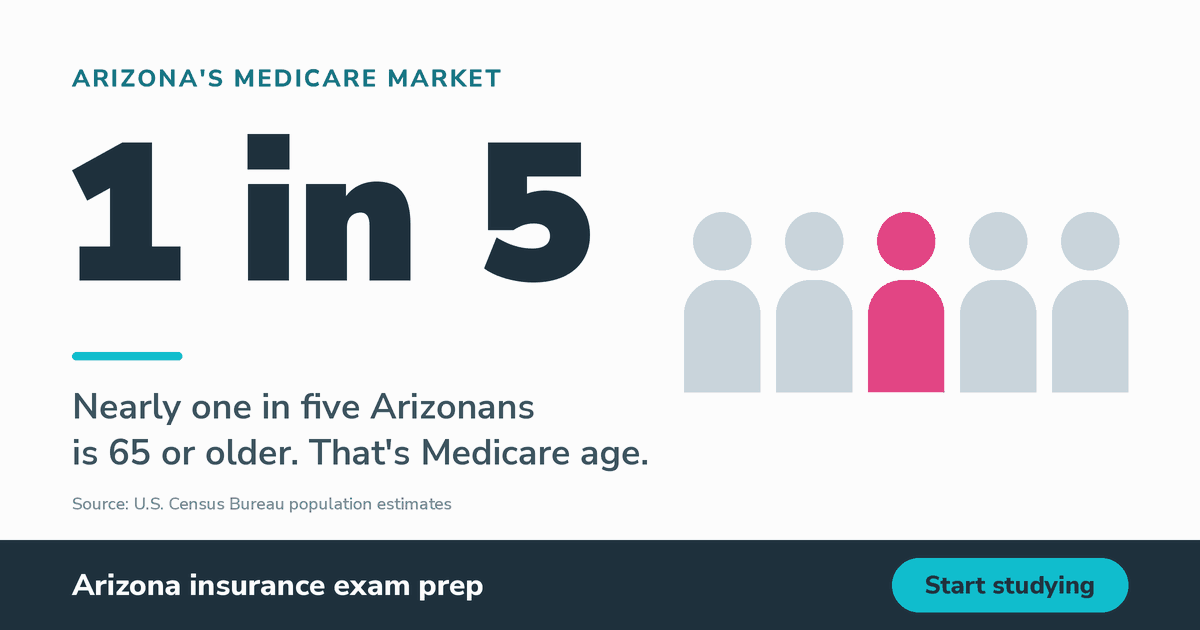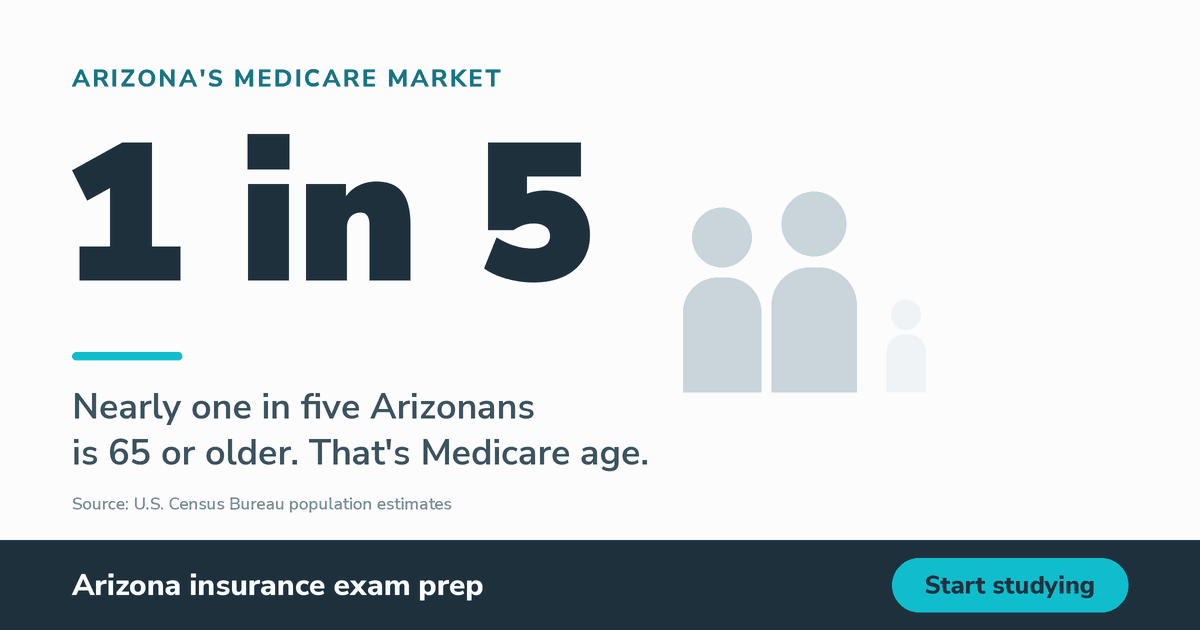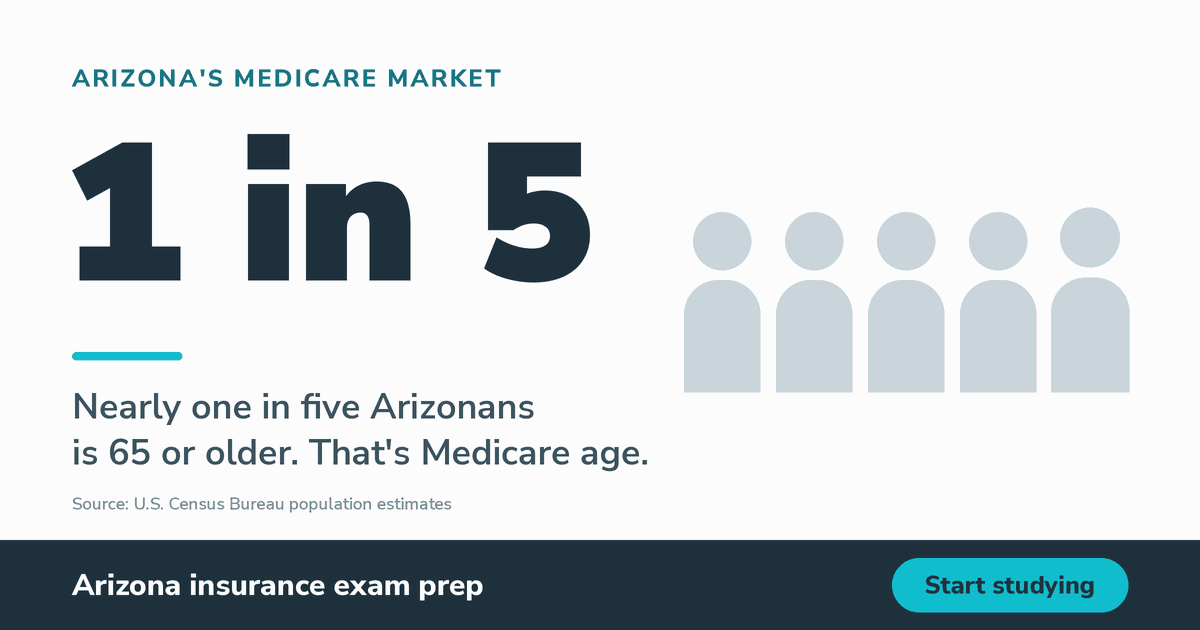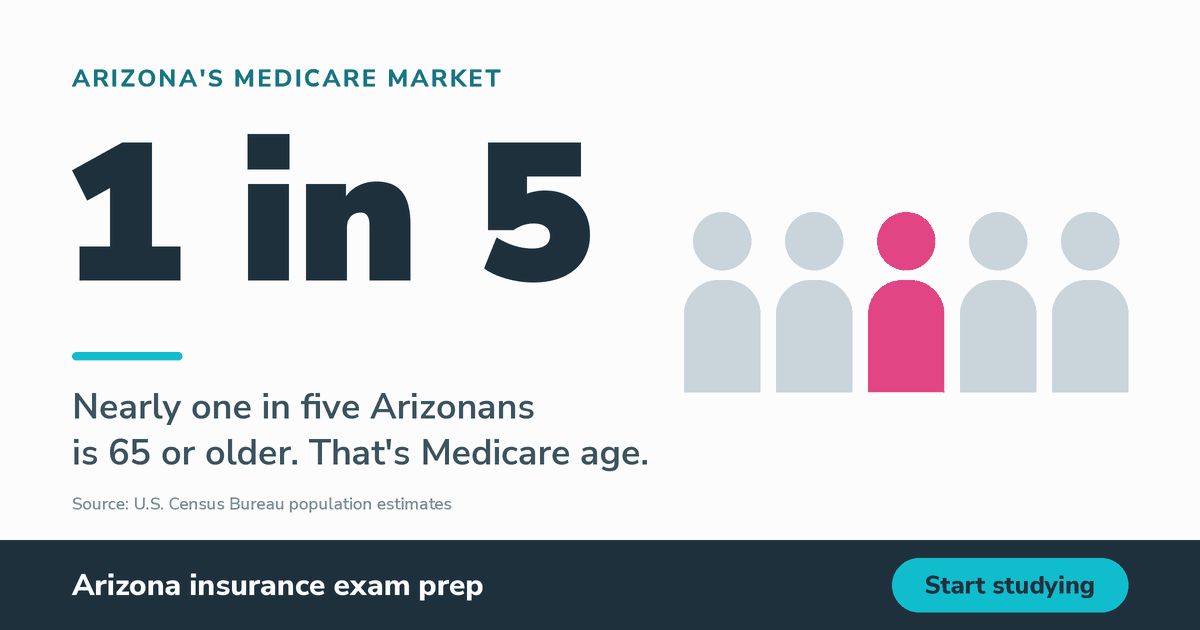
- The market is big and concentrated: Nearly 1 in 5 Arizonans is 65 or older, and more than half of the state's Medicare Advantage members live in Maricopa County.
- Retirement living started here: Youngtown opened as the first age restricted community in 1954, Sun City followed in 1960, and the metro now has more than 70 active adult communities.
- The calendar runs the business: Medicare's Annual Enrollment Period runs October 15 through December 7 every year, and agents must pass annual Medicare training plus carrier certifications before they sell.
- Your first step is a license: Medicare plans fall under the health line of an Arizona insurance license, which you earn by passing the state exam.
Phoenix may be the most natural place in the country to build a Medicare practice. Retirement communities were born here, the retiree population keeps growing, and the people who move here bring big questions about their coverage.
If you like helping people make sense of complicated choices, this is a market where that skill is in demand every fall. Here's what makes Phoenix different, what's changing for Medicare agents this season, and how to get licensed.
What makes Phoenix's retirement market different?
Retirement living started here
Arizona is the birthplace of age restricted retirement living. Youngtown, on the west side of the Valley, opened in 1954 as the first community with a minimum age requirement. Six years later, Del Webb opened Sun City right next door.
Sun City's debut on January 1, 1960 drew more than 100,000 visitors in a single weekend, about ten times what the developer expected. By the end of that first year, more than 2,000 homes had sold.
Today Sun City is home to about 40,000 people and roughly 28,000 homes. Sun City West, Sun City Grand, Sun City Festival, and Sun City Anthem at Merrill Ranch followed, and the wider metro now has more than 70 active adult communities.
Why retirees keep choosing Phoenix
- Taxes: Arizona doesn't tax Social Security benefits and has no estate or inheritance tax. Most other retirement income, like pension, 401(k), and IRA withdrawals, falls under the state's flat 2.5% income tax.
- Weather: Phoenix is known for 300+ sunny days a year and mild winters. Snowbirds start arriving in October, right as Medicare's busiest season opens.
- Healthcare: Banner Health and HonorHealth run large networks across the Valley, and Banner Boswell Medical Center sits right in Sun City.
- Community: Golf courses, pools, pickleball courts, and more than 120 chartered clubs in Sun City alone give new arrivals a built in social life.
All of that adds up to a big audience. According to Census dataFact Table AZ HCN010222 Quickfacts, about 1.5 million Arizonans were 65 or older in 2024.
How Phoenix compares with other retirement markets
Florida has more retirees overall, but they're spread across Miami, Tampa, Orlando, Jacksonville, and dozens of smaller metros. Phoenix packs its active adult communities into one metro area, so you can serve Sun City in the morning and Mesa in the afternoon.
The Bell Road corridor through Sun City, Sun City West, and Surprise is a good example: tens of thousands of retirees, their doctors, and their favorite lunch spots, all along one road.
Phoenix also has a deep insurance workforce. In May 2025 BLS dataWest News Release 2026 Occupationalemploymentandwages_phoenix_20260618.htm Regions, the metro employed insurance claims and policy processing clerks at 2.07 times the national rate.
What insurance do Phoenix retirees need help with?
Medicare decisions are the core of a senior market practice. Turning 65 opens a seven month Initial Enrollment Period, and every choice after that involves tradeoffs between cost, networks, and drug coverage.
- Medicare Advantage: Private plans that bundle hospital, medical, and usually drug coverage. More than 796,000 Arizonans were enrolled as of February 2026, according to Mark Farrah Associates' analysis of CMS data.
- Medicare Supplement (Medigap): Policies that cover the cost sharing Original Medicare leaves behind. They're popular with snowbirds, since Original Medicare and Medigap work with any provider nationwide that accepts Medicare.
- Part D: Standalone drug plans and the drug coverage built into most Advantage plans. Formularies vary a lot by carrier, so drug reviews are a big part of the job.
- Life, annuities, and long term care: Final expense coverage, guaranteed income from annuities, and long term care protection round out the conversation, since Medicare doesn't pay for most custodial care.
Most successful senior market agents pick a lane and go deep. Clients can tell the difference between someone who knows Medicare inside and out and someone who sells it on the side.
Choose a State and Course
Take control of your insurance career. Get the salary guide and start leveling up!
What's changing for Medicare agents this enrollment season?
Medicare rules and money shift every year, and the details for 2027 coverage are already set. Here's what Phoenix agents are working with this fall.
- Higher commission caps: CMS raised the maximum Medicare Advantage commission for 2027 enrollments to $725 for a new enrollment and $363 for a renewal in most states, including Arizona. Those are ceilings, not promises, and carriers can pay less.
- Carriers trimming pay on some plans: One of the largest Medicare Advantage carriers told marketing organizations it won't pay commissions on new enrollments in 123 plans across 33 states for 2027. Contracting with several carriers protects your income.
- New Part D numbers: The yearly cap on out of pocket Part D drug costs rises from $2,100 to $2,400 for 2027 coverage, along with a higher standard deductible. Clients will want someone to walk them through it.
- More certification options: AHIP's training for the 2027 plan year opened June 22, 2026, and agents must score at least 85% on annual testing. A growing number of carriers also accept NABIP's certification.
- Strict marketing timing: Agents can't start discussing next year's plans or collecting scopes of appointment until October 1.
The takeaway: Medicare Advantage is still the center of the market, but agents who also offer Medigap, final expense, and annuities are better protected when a single carrier changes course.
How does a Medicare agent's year actually work?
The enrollment calendar
Your year follows the official Medicare enrollment periods, and each one brings a different kind of client.
- Annual Enrollment Period (October 15 to December 7): Anyone with Medicare can join, switch, or drop Medicare Advantage and Part D plans for coverage that starts January 1. Most agents write the bulk of their Medicare business during these weeks.
- Medicare Advantage Open Enrollment Period (January 1 to March 31): People already in an Advantage plan get one chance to switch plans or return to Original Medicare.
- Initial Enrollment Periods: Someone in the Valley turns 65 every day. Their seven month window starts three months before their birthday month, which gives you steady work all year.
- Special Enrollment Periods: Moving, losing employer coverage, and other qualifying events open windows outside the usual calendar. Phoenix's steady stream of new arrivals makes these common.
Building a presence in 55+ communities
Relationships beat cold outreach here. Many communities host educational seminars where agents can teach without selling, and clubs, churches, and volunteer groups become your referral network over time.
CMS bans unsolicited door to door contact for Medicare sales, and many communities restrict solicitation anyway. The agents who last are the ones residents invite back.
Compliance basics
CMS regulates Medicare marketing closely. You'll need a documented scope of appointment before sales meetings, annual certification with every carrier you represent, and careful records. Carriers terminate agents who create regulatory risk, so compliance is a career skill, not paperwork.
How the income works
Medicare Advantage pays a flat initial commission in a client's first year, then a renewal each year they stay enrolled, so a book of loyal clients compounds over time. Medigap commissions are set by carriers and usually pay a percentage of premium.
Life insurance and annuity sales add another income stream. To see how senior market work stacks up against other top-paying roles, check our full breakdown.
What can slow you down
- Late certification: If your carrier training isn't finished when AEP opens, you can't sell those plans while demand peaks.
- Too few carriers: One contract leaves you stuck when a plan exits a county or stops paying commissions.
- Uneven cash flow: Most Medicare Advantage commissions arrive after coverage starts in January, so budget for the gap.
- Compliance slips: A missing scope of appointment or a pushy pitch can cost you your carrier appointments.
How do you get licensed to sell Medicare in Arizona?
Every Medicare career in Arizona starts with a state insurance license. Here's the path most Phoenix agents follow.
- Earn the health line on your license. Medicare Advantage, Medigap, and Part D are health products. Most senior market agents add the life line too, since final expense and annuities fall under it.
- Pass the Arizona state exam. The exam covers general insurance concepts plus Arizona law, and Aceable's Arizona exam prep is built to the state exam outline. See our exam pass rates breakdown before you book.
- Apply with the state. After you pass, you'll apply for your license and complete a fingerprint background check with the Arizona DIFI. Our Arizona licensing steps guide covers each one.
- Complete annual Medicare training. AHIP is the most widely accepted option, and some carriers also take NABIP or other approved programs. You'll need a score of at least 85%.
- Get appointed and certified with carriers. Each carrier requires its own product training every year before you can sell its plans.
- Add Arizona's product trainings. Selling annuities requires Arizona's annuity best interest training. Selling long term care requires an initial eight hour course plus four hours of ongoing training every two years.
Designations like the Certified Senior Advisor (CSA) can help you stand out once you're established. They aren't required, but they signal that you've invested in serving older clients well.
Phoenix rewards agents who show up prepared, stay compliant, and treat every client like a neighbor, because they usually are. New to the industry? Our guide for career changers covers what to expect, and these new agent tips help after you're licensed.
Frequently asked questions
Do I need a life insurance license to sell Medicare in Arizona?
No. Medicare Advantage, Medigap, and Part D fall under the health line. Many senior market agents add the life line anyway so they can offer final expense coverage and annuities.
When can I start selling Medicare after I get licensed?
Once you've completed annual Medicare training and your carrier certifications, you can help anyone who's in an enrollment window, any time of year. The Annual Enrollment Period each fall is the busiest stretch.
How much do Medicare agents earn per enrollment?
For 2027 coverage, CMS caps Medicare Advantage commissions at $725 for a new enrollment and $363 for a renewal in most states, including Arizona. Carriers can pay less, and some pay nothing on certain plans. Medigap pay is set by each carrier.
Is Phoenix a good market for new agents?
Yes, if you're ready to build relationships. The density of 55+ communities means less driving and more referrals, but plenty of agents work this market, so specialization and clean compliance set you apart.
Do snowbirds need different Medicare advice?
Often, yes. Many Advantage plans focus care on a local network, while Original Medicare with Medigap works with providers nationwide that accept Medicare. Clients who split the year between states need someone to compare those options with them.
Turn Sun City's questions into your career.
Your future in the insurance industry starts now.